Category Design vs Category Entry for B2B Startups
Choose the wrong strategy between category design and entry, and your growth stalls.
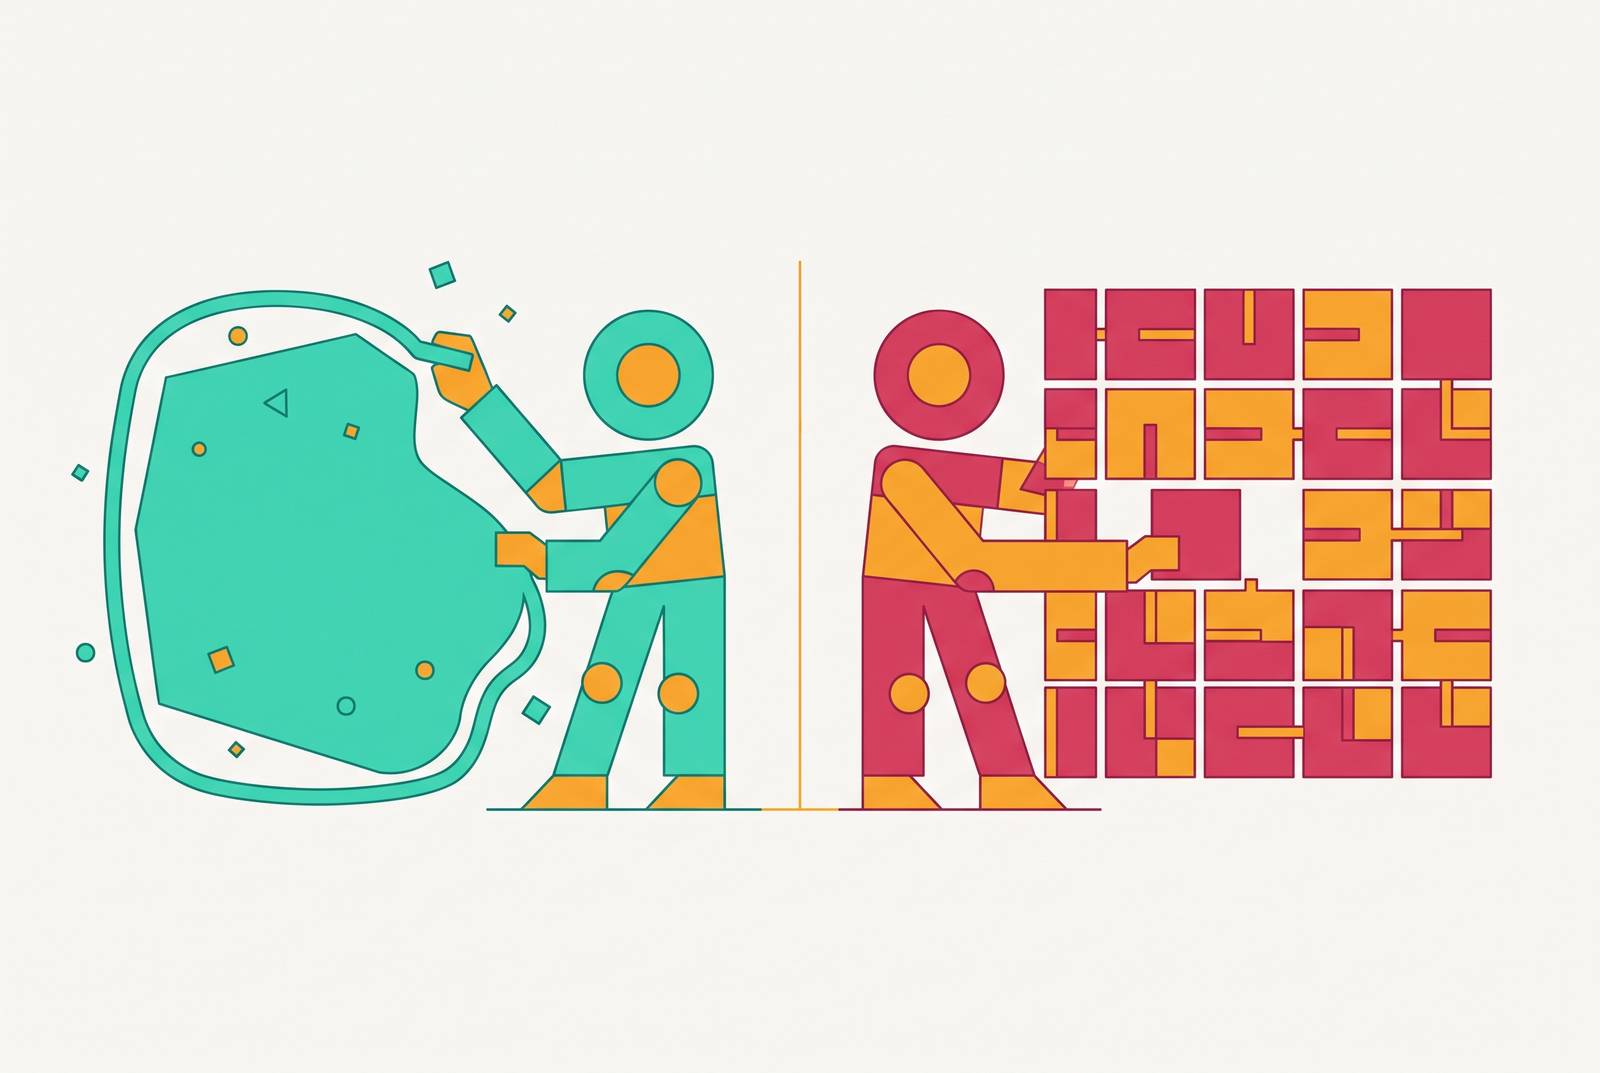
Most B2B founders treat this as a matter of taste, a branding preference to be decided in a slide deck. It's a constraints problem, and picking wrong in either direction is a reliable way to stall a company's growth rather than a positioning mistake that gets patched next quarter. The instinct usually starts with envy. A founder reads Play Bigger, watches a well-funded competitor launch under a bold new category name, and wants that same distance from the commodity conversation. That instinct makes sense on its face, but it mistakes a visible outcome for the conditions that actually produced it.
The opposite error is quieter: founders default to category entry because it feels cautious and cheap, without ever checking whether a real capability gap exists, one that buyers will notice and credit on their own. PitchKitchen's 2026 analysis frames the choice as neither permanent nor either-or in some abstract sense. It's about which constraint is actually binding right now, given the company's stage and the shape of its market. That's the question this piece works through, condition by condition, rather than starting from which strategy sounds more ambitious.
What category design requires before it is a viable option
Category design gets mistaken for a branding project. It's a business strategy that reorders product, pricing, sales motion, and internal operations around a market frame the company itself invents and then owns. That's a heavier lift than a new tagline, and it demands a specific kind of insight before it's worth attempting at all: not that the product is better than the alternatives, but that the problem buyers think they have is the wrong problem, or that a job exists that no current category name even describes.
Mike Damphousse calls the failure state "category jail": being stuck in a crowded space where buyers and analysts don't understand what a company is offering and why it's different, and the exit is not better messaging but a different game. Getting out of that jail doesn't come from sharper messaging. It comes from playing a different game entirely. One useful diagnostic for whether a company is even in that game: if its differentiation keeps landing on "better, faster, cheaper," it's speaking the language of competitive positioning, not category language, and that's a signal the conditions for category design probably aren't met yet.
Positioning clarity has to come first, and it isn't a parallel workstream a company can run alongside category design. PitchKitchen's 2026 framework states that most mid-market B2B companies need to nail positioning before category design is even relevant to them, and a category launch that skips this step produces what the framework calls beautiful language with no foundation under it. The same source offers a four-question test to run honestly before anyone commissions a category launch.
Can the company's three best sales reps explain, in one sentence each, who the ideal buyer is and what specific problem gets solved? Do current customers describe the product's value using language that actually matches what sales says in the room? And when a rep gets asked how the company differs from a named competitor, can they answer in one sharp sentence, without reaching for a feature list? A company that fumbles these questions has a positioning problem, not a category opportunity, and no amount of category language fixes that.
Timing is structural here. The same framework puts category adoption at 12 to 24 months of sustained market education before it locks in. A company without the runway to fund that window can't execute this strategy, no matter how sharp its category thesis is on paper. And the cost isn't hypothetical: Drift, Gong, and Datadog each burned significant capital before their category bets paid off. Category creation works, but it works expensively, and it works slowly, before it works at all.
What category entry requires (and where it breaks down)
Category entry is a legitimate primary strategy in its own right, viable whenever a real capability gap causes buyers to sort themselves toward the better option, with no need for anyone to invent a new category name to explain why.
Cursor makes the case. The AI capability gap was large enough that buyers recognized the difference themselves, without a category-education campaign teaching them what to look for. The mechanism at work is a new way to do a job buyers already had a budget line for, an existing workflow around, and a specific frustration with. The entrant just delivered a step-change improvement against a problem that already had a name.
The breakdown case looks different because it's easy to slide into: when the capability gap is incremental rather than a step-change, the entrant falls into the "better, faster, cheaper" trap, competing on features inside a crowded market where only a slice of total market value is even available to anyone but the leader. The A88Lab analysis documents this failure pattern directly: companies that try to out-innovate by bolting on more features and services to carve out a niche end up losing sight of the customer in the process, struggle to gain traction, and eventually fall off the radar entirely. Differentiation without a real distinction behind it is feature accumulation dressed up as a strategy.
Decide early whether the differentiation is horizontal or vertical. Horizontal SaaS, broad features that work across many industries, fits companies with a wide customer base and no single concentrated segment. Vertical SaaS, deep features built for one industry's specific workflow, fits companies where domain expertise is the actual moat. Getting this wrong doesn't sink a company outright, but it does mean building the wrong kind of depth for the buyers actually in the pipeline.
There's a newer risk specific to AI-adjacent categories, and it's structural rather than competitive. Foundation model providers and platform incumbents are actively reframing emerging AI capabilities as features of their own existing platforms. An entrant that doesn't move fast can watch its differentiation get absorbed before it ever compounds into something defensible. Speed is essential in this environment: a company that moves fast owns the wedge, while one that moves slowly watches it get folded into somebody else's roadmap.
The conditions that determine which path is available
Three conditions determine which path is actually open to a given company, and they need to be evaluated together, not one at a time: capital runway, buyer readiness, and market structure.
Start with capital and time. Category design needs enough runway to sustain 12 to 24 months of market education before adoption locks in. A company that starts down that road without that runway will run out of capital before analyst recognition and buyer vocabulary ever catch up to the pitch. There's a second clock running alongside the first: a company that takes longer than roughly 24 months to lock in analyst recognition risks having an incumbent simply reframe its category as a feature of an existing platform, a risk that's become concrete across the 2025-2026 AI platform landscape. Category entry doesn't carry either of these burdens. It requires a step-change capability gap, not a market education campaign, because the budget line already exists and the sales cycle runs against a problem buyers have already named for themselves.
Buyer readiness is the second condition, and it's shifted meaningfully in the last two years. Gartner's 2025 research found B2B buyers are, on average, far along in their purchasing process before they ever contact a provider directly. They arrive with a category frame already formed in their heads. Gartner's 2024 buyer research adds that a large majority of B2B buyers describe their purchase journey as complex or very complex already. Introducing a brand-new category name into that journey adds friction before it adds any clarity, and it makes an already difficult sale harder still. If buyers are actively searching for a solution to a problem they can already name, category entry captures demand that already exists. If the problem itself is unnamed, and buyers don't yet feel it as urgent, category design has to manufacture that demand from nothing, a fundamentally more expensive motion than capturing demand that's already moving.
Market structure closes the loop. If an existing category has a clear leader capturing most of the value in that space, entering it means fighting over what's left, a small fraction of the total. If the market's frame is genuinely wrong, if the problem buyers believe they have isn't their real problem, category design has real structural ground to build on. If the frame is correct and the product is simply better, that's a positioning problem being mistaken for a category opportunity. Mark Donnigan's framework offers a clean gut-check here: strip the company's name out of its own messaging. If a competitor's name slots in without changing the meaning of a single sentence, the company is stuck inside somebody else's category. It's stuck inside somebody else's.
How the two paths differ in execution, not just in concept
The most common failure is picking the right path and then executing the other one anyway. Founders who commit to category design but spend their days running competitive feature comparisons are burning the runway a category strategy needs. Founders who enter an established category but pour budget into market education nobody asked for are doing the reverse, and both mistakes are diagnosable from the outside long before revenue confirms them.
Category design has a specific set of artifacts that need to exist before launch, not after. The Category POV is at the center of it, a document, usually a few hundred words, that names the problem the market hasn't yet named, explains from first principles why the existing solutions fail, and positions the company as the only response that actually makes sense. Getting there requires executive alignment before anything goes external, not as a nice byproduct of good messaging but as a precondition for it. Damphousse's four-day category sprint exists specifically to force that alignment early, because a leadership team that describes the company differently in every conversation is the most visible signal of category jail.
Timelines differ sharply across these tools, and mixing them up wastes a company's calendar. Positioning locks in over six to twelve weeks. Category design takes 12 to 24 months to reach real market adoption. A company treating a category launch like a positioning refresh will get impatient and pull the plug just as the strategy starts working. Thought leadership is the engine that carries a category argument out into the world, toward analysts, buyers, and press. The Brixon Group's 2026 guide names three attributes that separate real category thought leadership from ordinary content marketing wearing category language as a costume: a genuinely unique perspective, a future-oriented vision, and practical relevance a buyer can act on.
AtoB positioned itself as the category leader in fleet fintech and grew from a small starting base into meaningful market share. TruckX grew its annual recurring revenue substantially over roughly 18 months by defining a new space inside freight tech. Both cases show that category design works at mid-market scale, provided the market structure conditions described earlier actually hold.
Category entry execution runs on a different logic entirely. If a product genuinely does a known job in a way that's immediately visible as different, the sales motion is demonstration rather than education. Vertical differentiation acts as a forcing function here: the A88Lab analysis points to industry-specific expertise, not feature accumulation, as the differentiation that actually holds up over time, because incumbents can't replicate deep domain knowledge overnight the way they can copy a feature. And the right sequencing for entry usually means going deep before going wide, finding the customers who are emotionally invested in the problem itself rather than just shopping for a solution to it. Those customers evangelize a product without anyone paying them to.
Why AI discoverability has become a third variable in this decision, regardless of which path a startup takes
Both paths now run through a filter that didn't exist a few years ago: whether AI answer engines actually surface a company's framing when a buyer sits down to research the problem. It's a measurable, manageable variable that sits on top of whichever strategy a company chooses.
The buyer behavior shift underneath this is substantial. By 2026, a large majority of B2B buyers use AI tools somewhere in their research process, and a G2 survey covering more than 1,000 B2B software buyers found that a strong majority say AI chatbots are actively changing how they research vendors, with ChatGPT the clear preferred tool by a wide margin over any other option. That changes what "buyer readiness" actually means in practice. Gartner's research finds that a buyer arriving with a category frame already formed increasingly formed that frame by asking an AI tool a question and taking its answer as a starting point rather than reading a comparison page a vendor wrote.
For a company designing a category, this raises the stakes on the Category POV in a way the original category design literature never had to account for. That document isn't just sales collateral or a press narrative anymore. It's the source material an AI system draws from when a buyer asks what problem a certain kind of company solves and why the usual solutions fall short. A category argument that never gets surfaced by the tools buyers actually use to research their problem fails invisibly. It fails invisibly, with no one ever hearing the pitch in the first place.
For a company entering an existing category, the stakes are just as high, if less obvious. A step-change capability gap only works as a strategy if buyers can actually discover it while comparing options, and increasingly that comparison happens inside a chat window before it happens on a company's own website. Whichever path a company has chosen, on the conditions laid out above, discoverability inside AI research tools is no longer a marketing afterthought bolted onto the strategy. It's a condition the strategy now has to satisfy on its own terms.
Sources
- Become a Market Leader with Thought-Leadership Category Design – The Practical Strategy Guide 2026
- B2B Category Design: Escape Crowded Markets Fast
- Category Design Strategies for B2B Founders to Own Your Market
- Category Design vs Positioning: Which Does Your B2B Company Need?
- The Dilemma of Category Creation vs. Differentiation in B2B SaaS